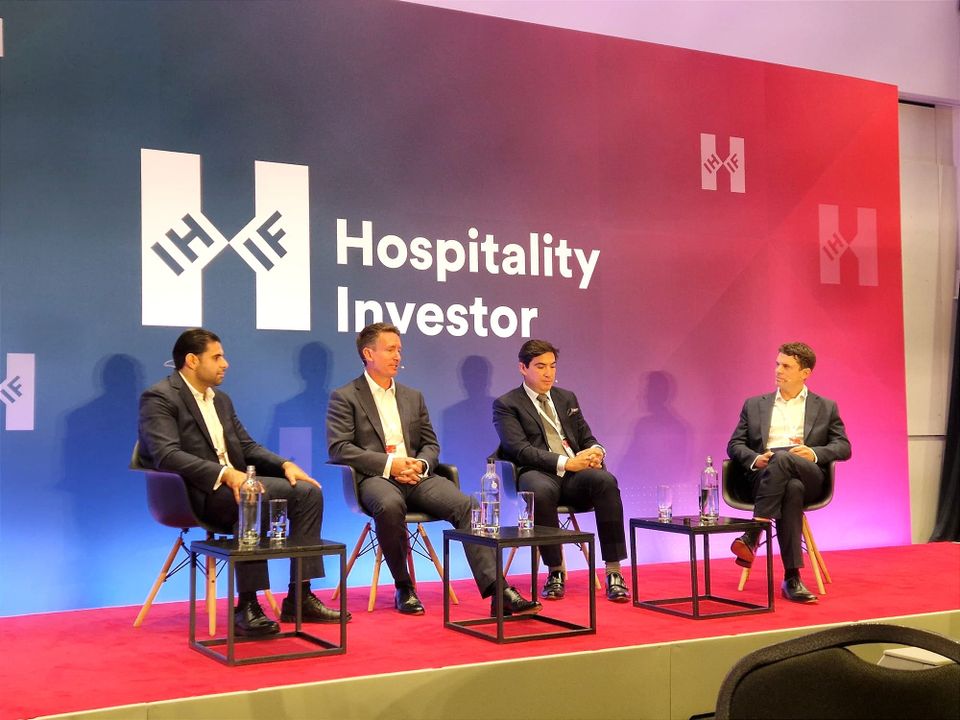
Hotels remain attractive to private equity because their operational complexity creates opportunities to improve performance. But with uncertain exits, higher capex requirements and limited room for financial engineering, investors are placing more weight on entry pricing, operational control and the ability to hold for longer when the original plan changes.
Private equity has not lost its appetite for hotels.
What has changed is the margin for error.
For investors underwriting hotels today, assumptions that once felt relatively comfortable have become much harder to rely on. ADR growth is less certain. NOI growth cannot simply be extrapolated forward. Exit yields remain difficult to predict, while refurbishment costs, labour, financing and regulatory expenditure can materially alter returns.
That pushes more of the investment case towards something investors can actually control: the price paid at acquisition.
Raoul Malhotra, Founder and CEO of Orka Investments, argued that while almost every variable can change during an investment period, entry pricing is fixed from day one.
“Your pricing is the one thing you have to get right day one.”
Raoul Malhotra
It sounds obvious. Yet in a market where buyers and sellers continue to disagree over values, getting that number right is increasingly where the investment thesis begins or ends.
A bad entry price is becoming harder to fix later
The traditional private equity model gives investors several ways to recover from an imperfect acquisition.
Revenue can grow faster than expected. Financing costs can fall. Yields can compress. The property can be sold into a stronger market.
Today, relying on those outcomes is much harder.
Charles Scudamore, Managing Director at Hetherley, pointed to deals that have failed for a wide range of reasons, from unbudgeted remedial capex to fire and life-safety issues and cladding. In many cases, the problem ultimately returns to the same question: whether the asking price properly reflects the work the buyer will have to undertake.
A £5 million problem discovered during diligence does not disappear because the seller did not originally account for it.
It becomes part of the acquisition price.
The same is true of optimistic operating assumptions. Repositioning a hotel, completing a refurbishment and stabilising performance can take considerably longer than a spreadsheet suggests.
Scudamore questioned business plans that assume a repositioned hotel can reach stabilised performance within three years, arguing that the reality can take substantially longer.
That matters because time itself has a price in private equity.
Every additional year affects IRR. Every delayed refurbishment pushes back stabilisation. Every slower exit increases the importance of the underlying cash flow.
A weak entry price therefore becomes increasingly difficult to rescue later.
Hotels remain attractive because they are difficult
Operational complexity is often described as one of the biggest risks in hotel investment.
It is also one of the reasons private equity likes the sector.
Hotels can absorb substantial capital, making them suitable for investors looking to deploy at scale. More importantly, they offer something long-duration real estate cannot: a revenue stream that can be repriced every day.
Malhotra described hotels as hard assets with a very short income duration. If the product is right and the operator can continue pushing ADR, some inflation can effectively be passed through to the customer.
That is particularly valuable after several years of pressure from wages, utilities and other operating costs.
A conventional landlord may have to wait years for a rent review or lease expiry. A hotel manager can change tomorrow night's rate today.
But that advantage only exists if the operation is capable of capturing it.
A poorly positioned hotel with weak revenue management does not automatically benefit from dynamic pricing simply because rooms are sold nightly.
The operational complexity that creates the opportunity also creates the execution risk.
Operations are moving closer to the investment decision
That is why the distinction between investor and operator is becoming less clear.
Some hotel investors have built their own operating or asset-management capabilities precisely because the P&L now requires so much attention.
Pierre-Edouard Vintrou described the advantage of being involved throughout the entire investment cycle, from origination and acquisition through asset management and eventual disposal. That means understanding not only the value per key, but the details of how the property actually operates.
Scudamore made the same point from a limited-service perspective.
Hotels with fewer food and beverage operations and a simpler service model offer fewer operational variables, but that does not make them passive investments. Revenue management, supplier contracts, staffing and cost control still require constant attention.
“You’ve got to get into the reeds of operations. I just don’t see that there’s another way.”
Charles Scudamore
That is an important shift.
Operations are not simply what happens after the acquisition team completes the deal. They are increasingly part of deciding whether the deal should happen at all.
The three-year exit is no longer guaranteed
Private equity is built around time.
Acquire, improve, exit.
But what happens when the market does not provide an attractive exit when the original business plan expects one?
The obvious temptation is to wait.
The problem is that waiting alone does not create value.
If an intended three to five-year hold becomes seven years, investors need to reconsider what can be done during the additional ownership period.
That could mean further refurbishment, renegotiating supplier contracts, reducing payroll costs, changing the operating model or investing in energy efficiency.
Scudamore's argument was simple: if the exit has been delayed, use the additional time to improve the asset rather than allowing the IRR clock to run while nothing changes.
That may also change how returns are judged.
Vintrou suggested that a longer ownership period can shift the emphasis from IRR towards equity multiple. A delayed exit may hurt annualised returns, but additional capex, ESG improvements or operational changes can still increase the total value ultimately created.
The distinction is increasingly relevant in a market where private equity may not always be able to choose the exact year in which it exits.
A longer hold can create a second business plan
An extended hold does not necessarily mean the original investment failed.
It can create an opportunity to reconsider decisions that were not initially part of the plan.
A hotel that was supposed to be sold quickly may suddenly justify a deeper refurbishment. An energy programme that seemed unnecessary on a three-year horizon might make sense over eight years. A brand agreement may approach expiry. An operator may no longer be the right fit.
In other words, a delayed exit can create a second investment thesis.
Branding is a good example.
A change from management agreement to franchise may create value in one property but destroy it in another once franchise fees and operational requirements are taken into account. Moving to another brand within the same family can sometimes reduce staffing, breakfast or service requirements without losing the distribution benefits of a larger system.
There is no universal answer.
The question is whether the operating structure improves the economics of that particular hotel.
Sometimes the absence of a brand creates liquidity
That principle becomes particularly interesting at the luxury end of the market.
Orka's redevelopment of the former Park Lane Mews in Mayfair illustrates why a brand is not always the obvious answer.
The hotel presented several challenges. The rooms were smaller than typical five-star brand requirements, with an expected average of around 22 square metres after redevelopment. Incorporating the property into a major international brand would have required fitting the development around brand standards that were not necessarily suited to the asset.
There was also an exit consideration.
A long hotel management agreement could reduce the number of potential future buyers. Keeping the hotel unbranded allows it to be offered as a freehold, flag-free asset, increasing flexibility for the next owner.
Operationally, Orka is positioning the hotel around roughly an £500 room rate in a Mayfair market where the highest end of the market can reach around £1,500, creating a product that does not neatly fit an existing brand category.
The example illustrates a broader principle.
A brand can create value through distribution, loyalty and recognition. But it can also create restrictions.
The decision should ultimately be judged against both operational performance and future liquidity.
Debt is available, but lenders are doing more homework
Higher interest rates might suggest that financing is the principal obstacle to hotel transactions.
The picture is more nuanced.
There remains substantial appetite from banks and alternative lenders for well-structured hotel investments, particularly where the location, operating team and underlying business are strong.
What has changed is the level of scrutiny.
Scudamore described lenders as considerably more forensic than they were 15 years ago. Hotel lending teams have become more experienced, meaning borrowers are likely to face more detailed questions about the operating plan, refurbishment and assumptions behind the investment.
That scrutiny can actually be useful.
Expensive or reluctant debt may not be what kills a deal. It may simply expose the fact that the deal was weak in the first place.
As Vintrou put it, there is plenty of leverage available, but the hotel should work operationally before the financing structure is layered on top.
“If the deal has to work because of structuring, then it’s not so much a hotel deal.”
Pierre-Edouard Vintrou
That is an important distinction in the current market.
Debt can enhance a strong investment. It should not be responsible for creating one.
Scale still creates liquidity
Private equity's preference for larger transactions is not just about deploying more money.
Scale can improve liquidity.
A £200 million hotel portfolio can appeal to a different buyer universe than twenty separate £10 million hotels. Larger transactions attract more institutional capital and can also support the development of an operating platform rather than simply a collection of properties.
Malhotra argued that this is where the real portfolio benefit can appear. It is not necessarily a premium paid directly for the real estate, but a broader pool of buyers and value attached to the operating platform itself.
The same applies to financing.
Larger lot sizes can make it easier for sophisticated lenders to deploy meaningful amounts of capital, while the hotel expertise within lenders has also improved considerably. Malhotra suggested that some capital which might previously have appeared as core equity now seems to be participating through the debt markets instead.
That helps explain why debt liquidity can appear relatively strong even while equity investors remain cautious.
Investors are finding new ways to exit without selling everything
A slower transaction market is also pushing investors to rethink what liquidity actually means.
A sale is not the only way to return capital.
Orka has used secondary recapitalisations in which the sponsor remains invested but the original joint venture partner is replaced by a new investor.
For the exiting investor, it provides liquidity.
For the incoming investor, the attraction is different. They enter several years into a business plan, after part of the operational or development risk has already been removed, and participate in the remaining upside.
This type of structure becomes particularly relevant when the hotel itself remains attractive but the original capital has reached the end of its preferred investment period.
Rather than forcing a full asset sale into a weak market, investors can change who owns the equity.
Financial engineering cannot replace hotel fundamentals
There is more capital available today than the term "private equity" alone suggests.
Family offices, institutions, operators and international investors are all participating in hotels. But that does not mean standards have fallen.
If anything, newer sources of capital are becoming more sophisticated.
Malhotra said family offices entering the sector can sometimes be more demanding on returns than traditional private equity, rather than passive sources of long-term money.
More investors therefore do not necessarily make weak deals easier to finance.
Hotel investments still have to compete with opportunities across other real estate sectors, other countries and increasingly other asset classes entirely.
That puts the emphasis back on fundamentals.
“If you’re falling back on, ‘let’s financial engineer a return here’, I think you’re probably stuffed.”
Charles Scudamore
The language may be blunt, but the principle is important.
If the underlying hotel cannot create an acceptable return through its location, product, operations and realistic improvement plan, changing the capital stack cannot permanently solve the problem.
The underestimated risk may be execution
Investors spend considerable time debating entry yields, exit cap rates, interest rates and macroeconomic conditions.
Those variables matter.
But one of the biggest risks may sit somewhere less visible: the gap between the business plan and actually delivering it.
Scudamore argued that macroeconomic risks may sometimes receive too much attention while delivery risk receives too little.
Travellers are still travelling. Hotels are still trading.
The harder question is whether the investor can actually deliver the refurbishment, ADR improvement, cost reductions and repositioning shown in the acquisition model.
Vintrou identified capex as another area where risk can be underestimated, particularly when traditional refurbishment requirements are combined with energy and ESG investment. Construction costs, labour, delays and the risk of failing to achieve the environmental standard expected by future institutional buyers can all affect exit liquidity.
The final valuation matters.
But investors have to reach the final valuation first.
The private equity model may need more patience
Perhaps the more fundamental question is not whether private equity can still invest successfully in hotels.
It can.
The question is whether every hotel opportunity fits neatly into the traditional model of buying, fixing and selling within five years.
Some will.
Others may produce attractive returns only when capital has the flexibility to hold for ten or even fifteen years.
Malhotra suggested that greater availability of capital with a longer-term mindset could unlock another part of the market, particularly investors capable of accepting a longer hold while still targeting private equity-style returns.
That could become increasingly important if owners remain reluctant to sell at today's pricing while buyers refuse to underwrite yesterday's valuations.
A tighter bid-ask spread would certainly help transaction volumes. So would more assets coming to market rather than lenders continually extending existing positions.
But the larger change may be philosophical.
Hotel investing has become less about predicting exactly when the market will provide an exit and more about owning an asset that remains worth improving while you wait.
Key takeaways
- Entry pricing has become more important. With less certainty around growth, financing and exit values, investors have fewer opportunities to correct an expensive acquisition later.
- Operational complexity remains part of the attraction. Hotels can reprice daily, but capturing that advantage requires much deeper involvement in the P&L.
- Hold periods need greater flexibility. A delayed exit can become an opportunity to improve operations, complete capex or reposition the asset rather than simply waiting for the market.
- Liquidity should influence operating decisions. Branding, ESG investment, portfolio structure and management agreements can all affect the future buyer pool.
- Debt is available, but more sophisticated. Lenders are increasingly capable of understanding hotel operations and can expose weaknesses in an investment case rather than simply preventing transactions.
- Financial engineering cannot replace fundamentals. Sustainable returns still depend on buying the right asset, executing the business plan and maintaining credible options if the original strategy changes.
Subscribe to our newsletter.
Become a subscriber receive the latest updates in your inbox.